First-Time Buyer Hub

Buying your first home?
Let's make it simple.

Every step from pre-approval to keys, in one place.
📍
Getting Ready
💰
Pre-Approval
🏠
Home Search
📝
Offer Accepted
🌟
Closing & Beyond
📚
Resources & FAQs
Bethany Kuhns holding a sold key sign

Welcome, first-time buyer! 🤍

Buying your first home is a big deal, and yes, it can feel like a lot. I've got you.

Pre-approval, touring, offers, inspections, appraisal, closing day. It's all here, in order, so you always know what's next.

No guessing. No confusion. Just a clear plan.

Questions along the way? I'm right here.

📅

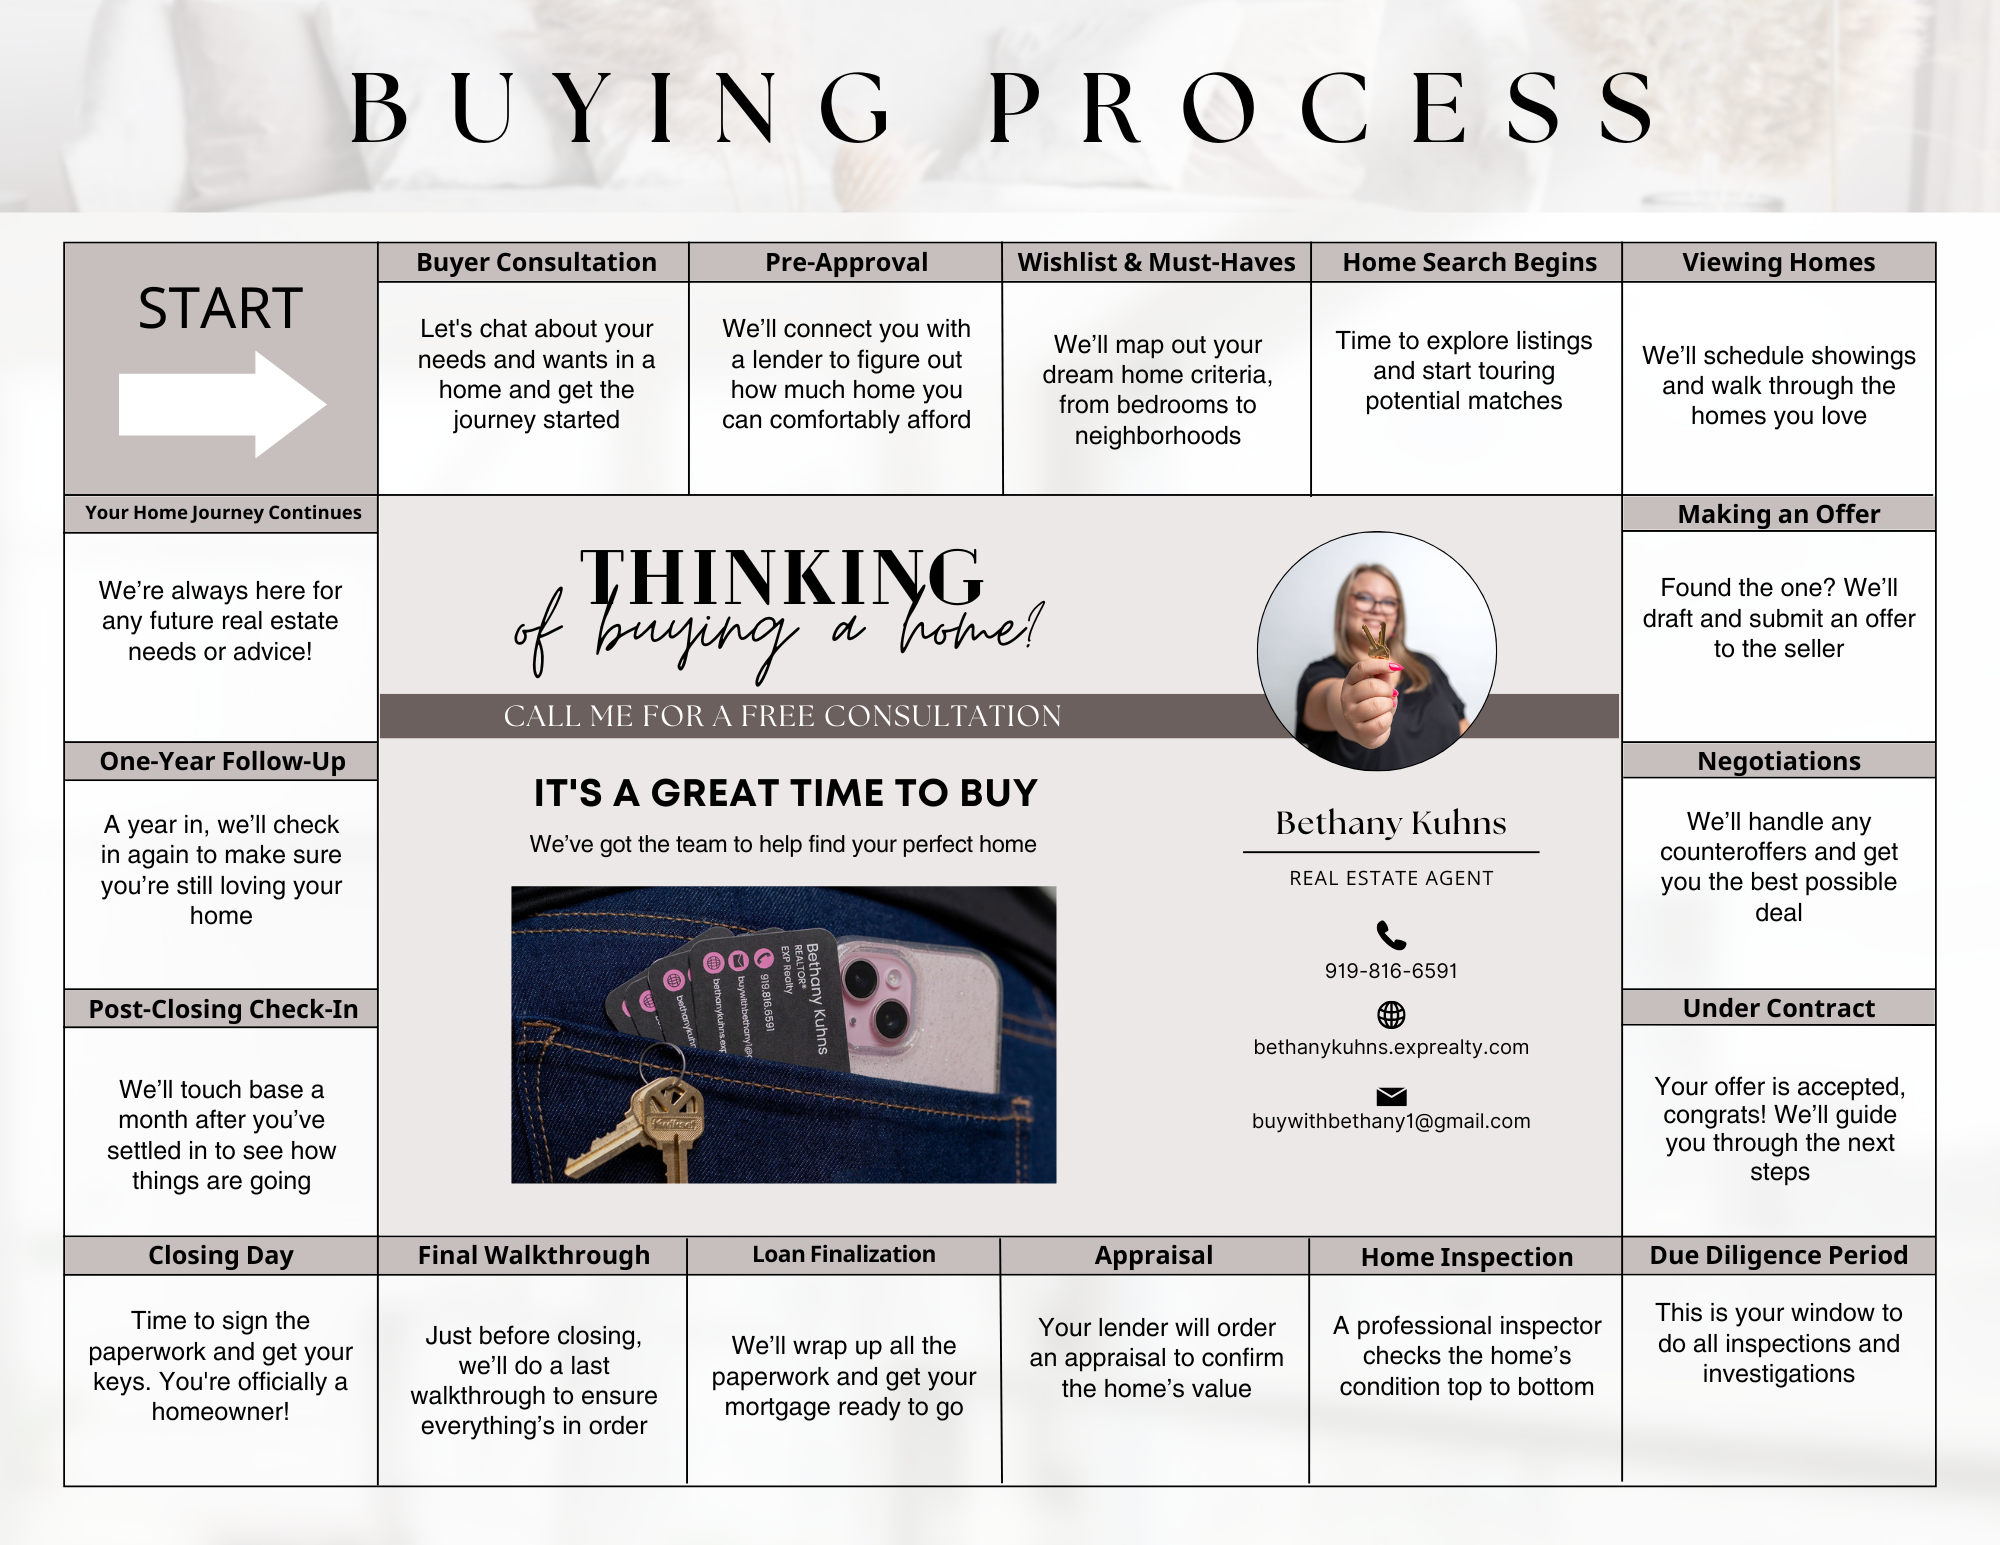
Buyer Timeline

Want the full big picture? Open the buyer timeline anytime for a simple view of each step from pre-approval to closing day.

Let's Get Connected

We will start with a buyer consultation so I can understand your goals, timeline, budget comfort, favorite areas, and what home needs to feel like for you. This hub is here to answer questions along the way, but our first step is getting your plan started together.

💬 Let's Get To Know Each Other
📝

Tell Me What You're Looking For

Fill out the quick buyer questionnaire so I can understand your goals, timeline, and budget before we connect. Most buyers finish it in about 5 minutes.

📄 Buyer Documents & Helpful Prep

Get Pre-Approved & Know Your Numbers

Before we get deep into showings, we need a clear financial lane. Your lender helps confirm what you can buy, and I help you think through what actually feels comfortable.

1
Connect With a Lender
A pre-approval helps us search accurately and write stronger offers when the right home appears.
2
Choose a Comfortable Payment
Your max approval and your ideal monthly payment may not be the same number, and that matters.
3
Plan Cash to Close
We will talk through down payment, closing costs, due diligence, earnest money, inspections, and appraisal.
4
Protect Your Approval
Before opening credit, moving money, or making a big purchase, check with your lender first.

Need help getting pre-approved?

These are trusted local lenders my buyers can connect with to start the financing conversation.
These lenders are provided as helpful resources. Buyers are always welcome to shop around and choose the lender that is the best fit for them.

💵 Money to Plan For
  • Down payment
  • Closing costs
  • Due diligence fee
  • Earnest money deposit
  • Home inspection and any specialty inspections
  • Appraisal and lender-related costs
⚠️ Protect Your Pre-Approval
  • Do not open new credit cards or loans without lender guidance.
  • Do not finance furniture, appliances, or a car before closing.
  • Do not move large sums of money without a paper trail.
  • Do not change jobs, pay structure, or work hours without checking first.
  • Respond quickly when your lender asks for documents.

Offer Accepted

Congratulations, you're under contract! Here's what happens from signed contract through inspections, appraisal, and lender milestones.

🕐 Key Milestones
Offer Accepted
You receive a full breakdown of price, due diligence fee, earnest money, contingencies, closing date, and next steps.
Due Diligence Money Paid
This is typically paid directly to the seller according to the contract terms and is usually nonrefundable once paid.
Earnest Money Deposited
Earnest money is deposited with the escrow holder, often within a few days of contract execution.
Inspections Scheduled
We schedule inspections quickly so you have time to understand the home and decide what to request.
Repair Negotiations
We review the inspection report together and decide whether to ask for repairs, credits, concessions, or no changes.
Appraisal
If financing is involved, your lender orders an appraisal to confirm the home's value supports the loan.
Clear to Close
Your lender approves final financing and the closing office prepares documents for signing.
🔍 What to Expect at Inspection
  • The inspector checks major systems including roof, HVAC, plumbing, electrical, structure, and appliances.
  • The inspection usually takes 2 to 4 hours, and it is helpful for you to attend the summary if possible.
  • We will review the report together and focus on safety, function, major costs, and your comfort level.
🤝 Negotiating Repairs

If repairs or credits make sense, we will strategize together. Options can include asking the seller to repair items, requesting a closing credit, adjusting terms, or moving forward as-is. You always choose what feels right for you.

What Is Due Diligence?

In North Carolina, the due diligence period is your protected time to investigate the home and decide whether you want to move forward. During this window, you may schedule inspections, review documents, confirm financing details, research insurance, and ask questions about the property.

  • Due diligence fee: This is paid directly to the seller based on the contract and is typically nonrefundable once paid.
  • Earnest money: This is held in escrow and may be refundable depending on timing and contract terms.
  • What happens during it: You may complete inspections, lender review, title review, insurance research, and any additional property research you choose.
  • Repair requests: If you want repairs, credits, or concessions, we will review what is reasonable and strategic before asking.
  • After due diligence ends: Your ability to terminate and keep earnest money becomes much more limited, so this date matters.
🔎 Inspections: Know What You're Buying

During your due diligence period, you have the opportunity to bring in professionals to evaluate the home. Here are the most common inspection types, we'll talk through which ones make sense for your specific property.

🏠 General Home Inspection
Always Recommended · $400 to $700

A licensed inspector evaluates the structure, roof, HVAC, plumbing, electrical, foundation, and more. This is the most important inspection and should be done on every purchase.

🌬️ Radon Test
Highly Recommended in NC · $150 to $250

Radon is a naturally occurring radioactive gas that's common in NC homes and is the second leading cause of lung cancer. Easy to test, easy to mitigate if elevated, always worth doing.

🐛 Termite / WDO Inspection
Recommended · $65 to $150

Checks for termites, wood-destroying organisms, and pest activity. Some lenders require this. Damage from pests can be very costly if not caught early, and treatments are typically straightforward.

❄️ HVAC Inspection
Recommended on Older Systems · $75 to $200

A specialist digs deeper into the heating and cooling systems than a general inspection. Particularly valuable if the system is aging or if the home uses a heat pump, mini-split, or geothermal system.

🍄 Mold Test
Situation Dependent · $200 to $600

If your general inspector flags moisture issues, musty smells, or visible discoloration, a mold test is a smart next step. NC's humidity makes mold more common than in drier climates.

🏚️ Roof Inspection
Recommended on Older Roofs · $150 to $350

A roofing specialist can assess remaining life, identify soft spots, damaged flashing, and granule loss that a general inspector may not catch in detail. Roof replacements run $8,000 to $20,000+ so this is worth knowing.

💧 Well Water Test
Required for Well Properties · $100 to $350

Tests water quality, flow rate, and pressure. Some lenders require a potability test for homes on well water. Covers bacteria, nitrates, and other common contaminants. Essential if the home isn't on city water.

🚽 Septic Inspection
Required for Septic Properties · $250 to $500

Evaluates the condition of the septic tank, drain field, and overall system function. Septic repairs can run $5,000 to $30,000+. If the home isn't connected to public sewer, this inspection is non-negotiable.

🔧 Sewer Scope
Recommended on Older Homes · $150 to $300

A camera is run through the sewer line from the home to the street to check for cracks, root intrusion, or collapse. Sewer line repairs can cost $5,000 to $25,000. A wise add-on for homes built before 1980 or with large trees near the home.

💡 We'll Walk Through This Together

Not every inspection applies to every property. I'll help you decide which ones make sense based on the age of the home, the area, the seller's disclosures, and what your general inspector finds. You'll never be doing this alone.

Closing & Beyond

The finish line is in sight. Here's what the final days look like and what to expect before keys are yours.

1

Loan & Appraisal

Your lender finalizes underwriting and confirms the appraisal supports the purchase price.

2

Final Walkthrough

You usually walk through 24 to 48 hours before closing to confirm the home is in the agreed upon condition.

3

Closing Day

Bring your photo ID and confirm wiring instructions directly with the closing office before sending funds.

4

Keys & Move In

Once everything records and funds, you receive keys and can celebrate the start of your next chapter.

⚡

After Closing

My commitment does not end when you get the keys. If you need vendor recommendations, have questions about your first weeks in the home, or want help planning future real estate moves, I am still here.

First-time buyer FAQ

A lender reviews your income, assets, debts and credit, then tells you how much they're willing to lend. It shows sellers you're ready and gives you a real budget before you tour.
No. Pre-qualification is a quick estimate based on what you tell the lender. Pre-approval means the lender has actually checked your documents and credit.
Closing costs are the fees to finalize your loan and purchase, things like lender fees, the attorney, title insurance and prepaid taxes and insurance. They're separate from your down payment. Sellers can sometimes agree to pay some of your closing costs, and we can ask for that in your offer. Another option is a 3-2-1 rate buydown, which lowers your interest rate for the first three years. It's often paid for by the seller or builder. Ask your lender how it would work for you.
A payment you make directly to the seller when your offer is accepted. It buys you time to inspect, get your appraisal and finalize your loan. It's usually nonrefundable once paid.
A good-faith deposit held in escrow, not paid to the seller. It shows you're serious and is usually applied toward your purchase at closing. Whether you get it back depends on your contract terms and timing.
The window in your contract to inspect the home, review the property, get the appraisal and line up your loan. If something isn't right, this is when you can negotiate or walk away.
For due diligence plus earnest money combined, plan for about 1 to 2% of the price. Your down payment and closing costs are separate and usually due at closing.
Yes. The NC Housing Finance Agency offers:
NC Home Advantage Mortgage™: down payment assistance up to 3% of the loan amount for first-time and move-up buyers, with an income limit of $158,000.
NC 1st Home Advantage Down Payment: $15,000 for eligible first-time buyers (no home as your main residence in the past three years) and military veterans.
Both are forgiven in years 11 to 15. You only repay if you sell, refinance or transfer the home before then. Ask your lender which programs you qualify for.
It depends. The search can be quick or take a while depending on what's available and what you want. Once you're under contract, many financed purchases close in about 30 to 45 days, depending on the contract and lender.
Having your own agent means someone is on your side for pricing, offers, negotiation and deadlines. In NC you'll review the Working with Real Estate Agents disclosure, and we'll sign a written buyer agreement before we tour homes together. It spells out what I'll do for you and how I'm paid, and that compensation is negotiable. Both are linked in this hub.
Love it! Just know the onsite agent at the model home works for and represents the builder. They're a great resource for the community and the homes, but their job is to look out for the builder. That's why it's smart to bring your own agent, ideally on your very first visit, since many builders require it. I'll be there for you.
Fill out the Get To Know You questionnaire, talk to a lender about pre-approval, and book a quick call with me so we can make your plan.

Everything Else You Need

👥

Need a Trusted Local Pro?

If you need help with lenders, inspectors, insurance, contractors, cleaners, movers, or anything else during the process, just reach out. I can help point you toward reliable local professionals.

📈

Estimated Cash to Close

Use this quick calculator to get a general idea of down payment, closing costs, and upfront deposits. Final numbers come from your lender and closing attorney.

📦

Moving Checklist

  • Schedule utility setup for closing day or move-in day.
  • Set up mail forwarding and update important accounts.
  • Confirm movers, truck rental, elevator reservations, or neighborhood access rules.
  • Pack daily items last and label boxes by room.
  • Keep closing documents, IDs, chargers, medications, and essentials easy to access.
💡

Touring Tips

  • Look at layout, light, storage, noise, parking, drainage, and maintenance needs.
  • Take notes right after each showing so homes do not blur together.
  • Do not fall in love with photos alone. Condition and location matter.
  • Ask what would be expensive, urgent, or hard to change later.
  • Trust the feeling, then verify it with facts.
📝

Offer Strategy Cheat Sheet

When you find the right home, we will look at the full picture together, not just price.

  • Price: What the home is worth based on comps and competition.
  • Due diligence fee: Money typically paid directly to the seller.
  • Earnest money: Money held in escrow.
  • Terms: Closing date, financing, inspections, appraisal, and seller concessions.
📌

Buyer Reminders

  • Check with your lender before moving money, opening credit, or making large purchases.
  • Do not wire funds until you have verified instructions directly with the closing office.
  • Keep inspection, appraisal, insurance, and lender deadlines on your radar.
  • Save receipts and documents related to the transaction.
  • Ask questions early. There are no silly questions in a real estate contract.

💬 Common Buyer Questions

Answers to the questions buyers ask most.

It is best to be pre-approved before serious touring. A pre-approval helps you understand your budget, move quickly when the right home appears, and write a stronger offer.
Common upfront costs include due diligence money, earnest money, inspections, appraisal, and sometimes lender fees. Your down payment and closing costs are usually due at closing. The exact numbers depend on your loan, offer terms, and property.
Due diligence money is typically paid directly to the seller and is usually nonrefundable once paid. Earnest money is held in escrow and may be refundable depending on timing and contract terms.
Yes. After inspections, we can ask for repairs, a credit, concessions, or another solution. The seller can agree, negotiate, or decline, so we will focus on what matters most and what supports your goals.
We will look at the loan type, appraisal gap, contract terms, seller position, and your comfort level. Options may include renegotiating, bringing additional funds, challenging the appraisal with supporting data, or using contract protections if available.
Sometimes buyers consider it in competitive situations, but it is a risk. I will help you understand the tradeoffs and consider safer ways to strengthen your offer without ignoring major unknowns.
The search can take days or months depending on inventory and your criteria. Once under contract, many financed purchases close in about 30 to 45 days, but timing depends on the contract and lender.
Yes, but it takes planning. We will talk through proceeds, timing, financing, contingencies, temporary housing, and your comfort level so the transition is as smooth as possible.
Usually after closing documents are signed, funds are received, and the deed records. Timing can vary by closing office and county, so we will confirm expectations before closing day.
Avoid opening new credit, making large purchases, changing jobs, moving large sums of money without documentation, or missing lender requests. When in doubt, ask your lender first.

Ready to take the first step?

Whether you're just starting to think about buying or you're ready to move fast, let's connect. I'll walk you through your options and make sure you feel confident every step of the way.
📞  Call or Text: 919-816-6591